Table of Contents
TL;DR
Net worth milestones are useful when they guide action rather than create anxiety. Your 20s are for building a financial base, your 30s for accelerating assets, your 40s for using peak earning years well, and your 50s for preparing income and assets for retirement. Federal Reserve medians offer a realistic comparison point, while your personal progress depends on debt, income, housing, family costs, and how consistently you save.
The Net Worth Milestone Checklist for Your 20s, 30s, 40s, and 50s
Why Age-Based Milestones Matter
Financial progress rarely moves in a straight line. A 24-year-old building emergency savings while repaying student debt may see little net worth growth at first. A 44-year-old with retirement investments and home equity may see larger annual increases, partly because assets have had more time to grow.
That is why the right financial priority changes with age. Early on, the goal is stability: avoiding costly debt, beginning retirement contributions and creating habits that continue for decades. In midlife, the emphasis often shifts toward increasing investment balances, reducing major liabilities and preparing for retirement.
The Federal Reserve’s 2022 Survey of Consumer Finances provides median family net worth figures by the age of the household reference person. These figures are useful benchmarks, but they are not required targets. A median means half of surveyed families in that group had more net worth and half had less. It does not account for your city, career timing, health costs, family needs or recent home purchase.
Salary-multiple goals, such as reaching three times income by age 40, are also planning guidelines rather than Federal Reserve standards. Use them to start a review, not to judge your entire financial life.
Your 20s: Build the Foundation Before Life Gets More Expensive
Federal Reserve Reference Point
The Federal Reserve reports a median net worth of $39,000 for families with a reference person under age 35. That category includes people beyond their 20s, so it should be treated as broad context rather than a precise age-29 target.
In your 20s, a positive and rising net worth is often a meaningful achievement. Education debt, entry-level earnings, rent, relocation costs and the expense of setting up adult life can all hold down the number temporarily.
The 20s Milestone Checklist
The strongest move in your 20s is building systems that work even when your income is still modest. Start by creating an emergency reserve. Three months of essential expenses is a solid initial target; growing that toward six months provides more protection as responsibilities increase.
When an employer offers a retirement match, contribute enough to receive the available match under your plan rules as early as your budget reasonably allows. Open an IRA, including a Roth IRA when eligible and suitable for your situation, if you want additional retirement saving outside a workplace account.
High-interest credit card balances should not become normal. Paying 20% or more in annual interest can undermine every other wealth-building effort. Student debt may take longer, but you should know the balance, interest rate and repayment plan rather than allowing it to remain an untracked expense.
By the end of your 20s, focus less on hitting a dramatic number and more on reaching a stable position: emergency savings available, costly consumer debt controlled, retirement contributions established and net worth moving upward.
Your 30s: Move From Stability to Acceleration
Federal Reserve Reference Point
The Federal Reserve age categories overlap with this decade. Families under 35 had median net worth of $39,000, while those aged 35 to 44 had median net worth of $135,600 in 2022.
That difference reflects a period when earnings, retirement contributions and home equity may begin to build more noticeably. It also reflects major financial pressures: childcare, housing costs, student loans and lifestyle inflation can absorb much of a rising income.
The 30s Milestone Checklist
A planning rule sometimes used in retirement discussions is to work toward net worth or retirement assets equal to roughly one year of salary around age 30 and several years of salary by around age 40. This is not an official benchmark, and it will not fit every household. Someone buying a first home, taking time away from work or repaying graduate-school debt may follow a different path.
The more practical checklist is behavioral. Eliminate high-interest consumer debt as early in the decade as possible. Maintain emergency cash rather than relying on credit for surprises. Increase retirement contributions after raises. When buying a home, choose a payment that still leaves room for investing and saving.
Homeownership can support net worth through equity, but purchasing property is not mandatory for financial progress. Someone renting affordably and investing consistently can still build strong assets. The essential question is where your surplus income is going.
Insurance also becomes more important when other people depend on your income. Term life insurance may be appropriate for parents, spouses with shared obligations or anyone whose death would leave another person financially exposed.
By your late 30s, the central measurement is simple: are your assets growing faster than your liabilities?
Your 40s: Use Stronger Earnings to Build the Balance Sheet
Federal Reserve Reference Point
For families with a reference person aged 45 to 54, the Federal Reserve reports median net worth of $247,200. For someone in the early 40s, the younger 35-to-44 benchmark of $135,600 may be the closer comparison.
Your 40s can become powerful wealth-building years. Many people have greater income than they did in their 20s or 30s, while earlier contributions may now be growing alongside new savings. But this decade can also bring expensive demands, such as supporting children, caring for parents or carrying a larger mortgage.
The 40s Milestone Checklist
Use this decade to increase the gap between what you earn and what you spend. If your income rises, assign part of each raise to retirement accounts, brokerage investments or debt reduction before lifestyle costs expand to consume it.
Consumer debt should be treated as a serious interruption to wealth building. Credit card balances and high-rate personal loans reduce both cash flow and net worth at a time when retirement preparation becomes more urgent.
Review your asset mix as well. Holding everything in employer stock, one business or home equity can create unnecessary concentration risk. A diversified investment approach cannot remove market risk, but it can avoid depending on one asset for your future.
When education funding is part of your family plan, a 529 account may help support qualified education expenses, but it should not replace your own retirement saving. Your child may have education funding options later; you cannot borrow your way through retirement.
Some planning frameworks suggest working toward net worth of several times annual income by the middle or end of this decade. Treat that as a conversation starter. Your more important target is an improving balance sheet with retirement savings growing, costly debt controlled and emergency reserves intact.
Your 50s: Prepare Assets to Support Life After Work
Federal Reserve Reference Point
The Federal Reserve reports median net worth of $364,500 for families with a reference person aged 55 to 64. This benchmark includes home equity and all other assets minus liabilities, so it does not by itself show how much retirement income a household can generate.
In your 50s, the question changes. It is no longer only, “How much can I build?” It becomes, “How will these assets support my spending when work income slows or ends?”
The 50s Milestone Checklist
Retirement contribution limits can give people in this decade additional room to save. For 2026, the IRS states that the employee elective deferral limit for many 401(k), 403(b), governmental 457 plans and the federal Thrift Savings Plan is $24,500. Participants aged 50 or older may generally contribute an additional $8,000 in catch-up contributions where their plan permits it. For participants aged 60 through 63, a higher 2026 catch-up limit of $11,250 applies to many of these plans.
Use this decade to review retirement income sources, not only account balances. Estimate Social Security benefits, evaluate pension income where applicable and consider how withdrawals from retirement accounts will support your living expenses.
Debt deserves a fresh review too. Carrying a manageable mortgage into retirement is not automatically a mistake, especially when the rate is low and assets are strong. But high-interest consumer debt or a housing payment that requires continued full-time income can limit future flexibility.
Portfolio risk also matters more when withdrawals are approaching. A sharp market decline just before or early in retirement can be especially difficult when you must sell investments to pay living expenses. Review your time horizon, cash reserves and asset allocation with that reality in mind.
A rule-of-thumb goal of seven to ten times annual salary near age 60 may be useful for some households, but it is not a universal requirement. Spending level, Social Security, pensions, housing costs and retirement age all affect what you need.
How to Check Your Current Position Against Benchmarks
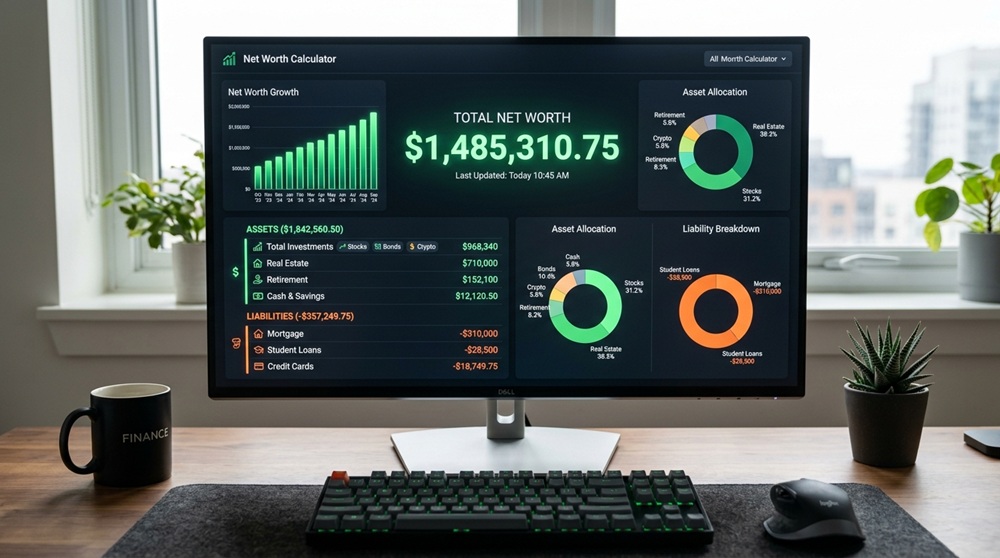
Begin with a complete net worth calculation:
Net Worth = Total Assets − Total Liabilities
Include cash, retirement accounts, taxable investments, home equity, vehicles at resale value and business equity where it can be valued conservatively. Subtract mortgages, auto loans, student loans, credit cards, tax debt and any other current liabilities.
The Federal Reserve’s 2022 median family net worth benchmarks are:
| Age of Reference Person | Median Net Worth |
| Under 35 | $39,000 |
| 35–44 | $135,600 |
| 45–54 | $247,200 |
| 55–64 | $364,500 |
| 65–74 | $409,900 |
| 75 or older | $335,600 |
A tool with a built-in U.S. age benchmark can help you calculate your total assets and liabilities, then compare the result with the Federal Reserve age bracket relevant to you.
Do not stop at the comparison. Look at what your number is made of. A $300,000 net worth held almost entirely in home equity is different from a $300,000 net worth spread across cash, retirement investments and manageable home equity. Total value matters, but liquidity and diversification matter too.
What to Do When You Are Behind
A benchmark is information, not a verdict. Being below the median does not tell you why you are there or what happens next. A late career start, divorce, student debt, health costs, caregiving or a recent home purchase can all affect the number.
Choose the highest-leverage action for your current decade. In your 20s, that may be clearing a credit card balance and beginning retirement contributions. In your 30s, it may be increasing savings after a raise rather than upgrading lifestyle costs. In your 40s, it may be eliminating consumer debt and increasing invested assets. In your 50s, it may be using catch-up contribution room, reviewing retirement income and reducing financial obligations before work becomes optional.
Recalculate every three to six months. You are looking for direction: liabilities declining, assets increasing and your plan becoming easier to maintain.
For further practical guidance on building and measuring personal wealth, NetlyWorth provides resources focused on clear financial tracking and everyday decision-making.
The Checklist Is a Map, Not a Verdict
Age-based milestones help because they tell you which questions deserve attention now. They do not decide your future. Calculate your current net worth, compare it with a realistic benchmark and identify the one move that can make the largest difference this year. The goal is not to match someone else’s timeline. It is to build a balance sheet that gives your future self more choices.